Announcement on Bursa Malaysia: Quarterly report for the financial period ended 30 June 2026, with press release (26 August 2026)
KUALA LUMPUR, 26 August 2026: Catcha Digital Berhad (“Catcha Digital” or the “Group”) today announced its unaudited financial results for the second quarter and half-year ended 30 June 2026 (“Q2 FY2026” and “H1 FY2026”).
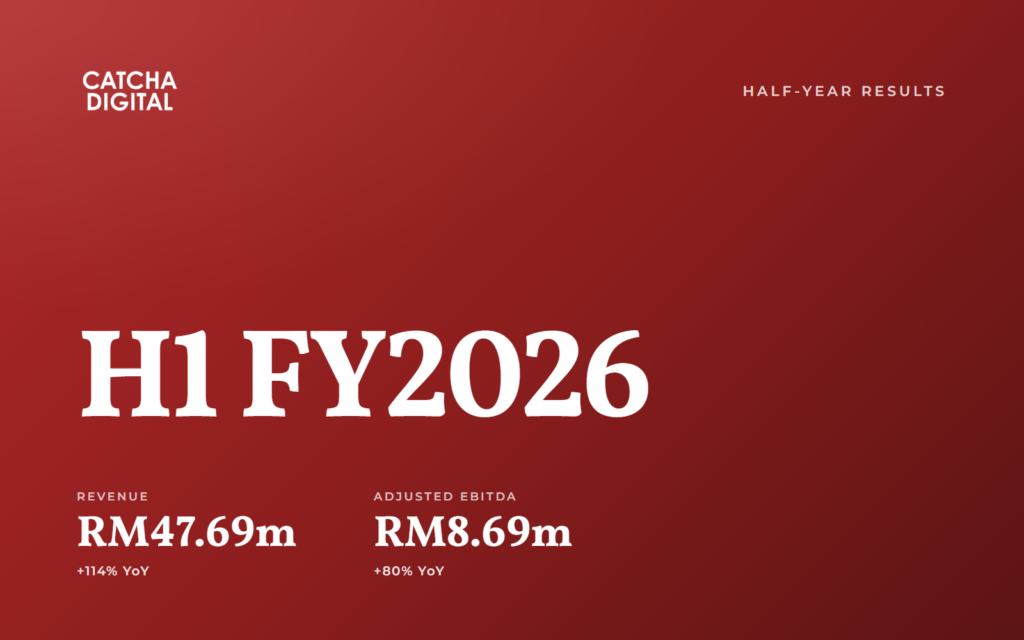
For the half-year ended 30 June 2026, the Group achieved the following financial results compared to the corresponding period of the prior financial year (“H1 FY2025”):
- Revenue of RM47.69 million, up 114% year-on-year
- Adjusted EBITDA* of RM8.69 million, up 80% year-on-year
- Adjusted PATAMI* of RM3.64 million, up 14% year-on-year
- Statutory LATAMI of RM1.69 million, arising substantially from non-cash and acquisition-related charges (see reconciliation below)
- Cash and cash equivalents of RM30.40 million as at 30 June 2026
“We are two years into building a permanent home for market-leading companies . The revenue has been growing meaningfully, our half-year revenue more than doubled year-on-year and our adjusted EBITDA grew 80%, which tells us the underlying platform is compounding as intended. The statutory loss reflects the accounting cost of acquiring eight businesses in fifteen months and not the cost of operating them,” said Eric Tan, Group Chief Executive Officer of Catcha Digital.
Record Half-Year Revenue Driven by the Digital Media Portfolio
The digital media segment was the primary driver of the Group’s revenue growth, contributing RM20.77 million in Q2 FY2026 (Q2 FY2025: RM12.38 million) and RM46.41 million in H1 FY2026 (H1 FY2025: RM21.61 million, accounting for the majority of the Group’s revenue in both periods and driving the Group’s overall 68% and 115% revenue growth for the quarter and half-year respectively.
Digital media remained the Group’s core earnings engine in Q2 FY2026. Digital media delivered adjusted EBITDA of RM4.69 million in Q2 FY2026 (Q2 FY2025: RM3.77 million) and RM11.72 million in H1 FY2026 (H1 FY2025: RM5.85 million), reflecting a 24% and 100% adjusted EBITDA increase for the quarter and half-year respectively.
The overall group’s Q2 adjusted EBITDA and adjusted PATAMI moderation reflects the seasonal absence of B2B Expo exhibitions in the quarter and the increase in investment in the holding company, rather than any softening of the underlying core digital media business.
Earnings Inflection: B2B Expo Weighted to the Second Half
The B2B Expo segment held no exhibitions in the quarter and therefore incurred fixed operating costs without corresponding revenue, recording an adjusted LATAMI of RM0.45 million. The segment was only established in Q3 FY2025 and is accordingly absent from the Q2 FY2025 comparative.
The segment’s flagship exhibitions for FY2026 are scheduled to be held in Q3 FY2026, and the revenue and profit contribution of the segment for the financial year is therefore expected to be concentrated in the second half. The segment, comprising Agri Malaysia, MBAM OneBuild and the Malaysian International Food and Beverage Trade Fair (“MIFB”).
Strong Capital Position to Continue Executing the Acquisition Strategy
This acquisition-led expansion is supported by a solid capital base. The Group has a RM35 million Revolving Credit Facility with Affin Hwang Investment Bank Berhad and the potential to raise up to an additional RM73 million upon full exercise of the outstanding warrants issued under the Rights Issue completed in 2025. Consistent with the Group’s policy of funding growth from operating cash flow first, then debt, then equity, the warrant proceeds remain a reserve source rather than a primary funding mechanism. As at 30 June 2026, the Group held cash and cash equivalents of RM30.40 million against total bank borrowings of approximately RM12.29 million.
“We now have a growing portfolio across three verticals and eight acquisitions expected to contribute for a full financial year in FY2026. With our B2B Expo exhibitions weighted to the second half, we expect earnings to inflect through the remainder of the year and ending FY2026 with meaningful growth compared to 2025. We remain committed to the long-term compounding of free cash flow, and we are as excited as ever about partnering with great entrepreneurs building category-defining businesses,” says Patrick Grove, Chairman of Catcha Digital.
Catcha Digital has completed 7 acquisitions in 2025 and 1 acquisition in Q1 FY2026, each positioned to strengthen its foothold in the digital media, B2B expo and IT solution space, all expected to contribute positively to future earnings. No new acquisitions were completed during Q2 FY2026. The completed acquisitions are set out below.
- On 31 March 2026, Catcha Digital completed an acquisition of 100% equity interest in ExpoCO Sdn Bhd (“MIFB”) (formerly known as Constellar Exhibitions Malaysia Sdn Bhd) for a cash consideration of RM3.97 million due at Completion Date, via the Group’s 60% direct subsidiary, One International, giving the Group a 60% effective equity interest of MIFB.
- On 22 December 2025, Catcha Digital completed an acquisition of 50% equity interest in Headline Media Sdn Bhd, the owner of digital platforms including Weirdkaya, LokLokWords and Ezlokal Food, raising its total equity interest to 80%. The payment, to be made in two tranches over 12 months, consisting of RM0.80 million due at Completion Date and RM3.20 million due 12 months after Completion Date.
- On 17 December 2025, Catcha Digital completed an acquisition of 60% equity interest in Framemotion Studio Sdn Bhd (“Framemotion”) for RM37.32 million. The payment, to be made in three tranches over 24 months, is contingent on Framemotion achieving a profit after tax and minority interest of RM6.8 million in the first 12 months post-completion and RM6.8 million in the subsequent 12 months.
- On 5 December 2025, Catcha Digital completed an acquisition of 100% equity interest in Maxoom Sdn Bhd for RM6.13 million. The payment, to be made in two tranches over 12 months, consisting of RM1.80 million due on the Completion Date and a Post-Completion Sum of RM4.33 million due 12 months after the Completion Date. The acquisition includes a Net Asset Guarantee of RM0.89 million at the Completion Accounts Date.
- On 27 August 2025, Catcha Digital completed an acquisition of 60% equity interest in One International Exhibition Sdn Bhd (“One International”) for RM11.38 million. The payment, to be made in three tranches over 24 months, is contingent on One International achieving a profit after tax and minority interest of RM2.75 million in the first 12 months post-completion and RM3.16 million in the subsequent 12 months.
- On 18 June 2025, Catcha Digital completed an acquisition of 70% equity interest in Tastefully Malaysia Sdn Bhd (“Tastefully”) for RM7.6 million. The payment, to be made in four tranches over 36 months, is contingent on Tastefully achieving a PAT of RM0.5 million for the FYE 2024, RM1.1 million for the first 12 months after completion, RM1.4 million for the subsequent 12 months, and RM1.6 million for the final 12 months.
- On 7 May 2025, Catcha Digital completed an acquisition of 60% equity interest in Drive 2 Digital Sdn Bhd (“D2D”) for RM16.2 million. The payment, to be made in three tranches over 24 months, is contingent on D2D achieving a PAT of RM3.5 million in the first 12 months post-completion and RM4.2 million in the subsequent 12 months.
- On 22 January 2025, Catcha Digital completed an acquisition of 51% equity interest in Nexible Solutions Sdn Bhd (“Nexible”) for RM11.3 million. The purchase considerations are to be paid in four tranches and is tied to the achievement of the profit after tax guarantee (“PAT Guarantee”) over the period of 36 months, broken down into PAT Guarantee of RM0.7 million, RM1.2 million, RM2.2 million and RM3.3 million for the 12-month period ended 31 December 2024, 31 December 2026, 31 December 2027 and 31 December 2028 respectively.
NOTES:
* Reconciliation of Adjusted Operating Performance
To provide a clearer view of the Group’s operating performance, Catcha Digital presents its financial performance on an adjusted basis using Alternative Performance Measures (“APM”). The adjustments primarily involve non-recurring, non-cash items or items directly attributable to acquisition activity. The Group believes that they help to effectively monitor the performance of the Group and support readers of the financial statements in drawing comparisons with past performance, and considers the APMs to be a more representative view of the Group’s underlying operating profitability.
The following tables outline the key adjusted metrics on an individual-quarter (Q2) and cumulative half-year (H1) basis:
Individual Quarter
| in (RM’000) | Q2 FY2025 | Q2 FY2026 |
|---|---|---|
| EBITDA (Statutory) | 2,951 | 2,820 |
| PATAMI / (LATAMI) (Statutory) | 1,725 | (532) |
| EPS / (LPS) (Statutory) | 0.64 sen | (0.12) sen |
| Adjustments in EBITDA: | ||
| (+) M&A financing cost – Facility fee | – | 58 |
| (+) M&A transaction cost – Due diligence | 49 | 79 |
| (+) LTIP costs and other non-operating costs | – | 1 |
| Total adjustments in EBITDA | 49 | 138 |
| Adjustments in PATAMI: | ||
| (+) Adjustments in EBITDA (as above) | 49 | 138 |
| (+) Unwinding of interest on deferred purchase consideration (non-cash) | 161 | 812 |
| (+) Amortisation of intangible assets – In relation to M&A | – | 139 |
| (+) M&A financing cost – Interest paid related to financing of M&A | 15 | 238 |
| Total adjustments in PATAMI | 225 | 1,327 |
| APMs: | ||
| Adjusted EBITDA | 3,000 | 2,958 |
| Adjusted EBITDA per share | 1.11 sen | 0.65 sen |
| Adjusted PATAMI | 1,950 | 795 |
| Adjusted EPS | 0.72 sen | 0.17 sen |
Cumulative (Half-Year)
| in (RM’000) | H1 FY2025 | H1 FY2026 |
|---|---|---|
| EBITDA (Statutory) | 4,861 | 5,719 |
| PATAMI / (LATAMI) (Statutory) | 3,051 | (1,694) |
| EPS / (LPS) (Statutory) | 1.13 sen | (0.37) sen |
| Adjustments in EBITDA: | ||
| (+) M&A financing cost – Facility fee | – | 113 |
| (+) M&A transaction cost – Due diligence | 83 | 536 |
| (+) LTIP costs and other non-operating costs | – | 2,321 |
| (+) Gain on waiver of debt (non-operating) | (123) | – |
| Total adjustments in EBITDA | (40) | 2,970 |
| Adjustments in PATAMI: | ||
| (+) Adjustments in EBITDA (as above) | (40) | 2,970 |
| (+) Unwinding of interest on deferred purchase consideration (non-cash) | 161 | 1,619 |
| (+) Amortisation of intangible assets – In relation to M&A | – | 278 |
| (+) M&A financing cost – Interest paid related to financing of M&A | 24 | 468 |
| Total adjustments in PATAMI | 145 | 5,335 |
| APMs: | ||
| Adjusted EBITDA | 4,821 | 8,689 |
| Adjusted EBITDA per share | 1.79 sen | 1.91 sen |
| Adjusted PATAMI | 3,196 | 3,641 |
| Adjusted EPS | 1.19 sen | 0.80 sen |
| Adjusted EBITDA Growth Rate YoY | +80% | |
| Adjusted PATAMI Growth Rate YoY | +14% | |
| Revenue Growth Rate YoY | +114% |
Adjustments include charges that are non-recurring, non-cash items or directly attributable to acquisition activity, such as the one-off LTIP charge, unwinding of interest on deferred consideration, and PPA-related amortisation, of which details can be found in the Group’s Q2 FY2026 Interim Report available on the Company’s website and on Bursa Malaysia.
¹ The Group excludes non-cash gains arising from the waiver of debt due to restructuring or adjustments to purchase considerations. While these gains reflect successful strategic negotiations, they are non-cash in nature and are excluded to provide a more conservative and consistent view of the Group’s recurring operating income.
² The Group excludes the non-cash effect of the unwinding of interest on deferred purchase considerations. This is a technical MFRS requirement to reflect the time value of money for future payment tranches. It does not represent cash interest paid during the period.
³ The Group excludes the effect of amortisation of intangible assets arising from Purchase Price Allocation exercises. Amortisation is non-cash and is significantly affected by the timing and size of the Group’s acquisitions. While these intangible assets contribute to revenue generation, the amortisation charges are inconsistent in frequency and do not reflect the Group’s underlying cash-generating position.
⁴ Adjusted EPS and Adjusted EBITDA per share are calculated based on a weighted average of 455.54 million and 269.46 million shares outstanding during FY2026 and FY2025 periods respectively.
END OF PRESS RELEASE
For further information, kindly contact:
Catcha Digital Berhad
Eric Tan – Group Chief Executive Officer
Email: [email protected]
About Catcha Digital Berhad
Catcha Digital Berhad, an investment holding company based in Malaysia, operates primarily in the digital media, B2B expo and IT solution sectors.
iMedia Asia Sdn Bhd, a subsidiary under the digital media sector, is a digital media company that offers integrated advertising solutions to major brands across various industries in Malaysia. Its media assets include OhMedia, Beautifulnara, Weirdkaya, Goody25, The Reporter, Moretify, KS Lagi, iCanvas, Ittify, as well as the leading automotive digital media brands such as Automachi, Auto123, Careta, and Mekanika, the leading consumer technology media brands under Technave, the leading experiential marketing company, Framemotion, and the leading consumer food expo in Malaysia, Tastefully.
One International Exhibition Sdn Bhd, a subsidiary under the B2B Expo sector, is a leading exhibition and event organiser in Malaysia. It specialises in organising large-scale B2B trade exhibition for key industries, including agriculture, construction and food and beverage, with flagship exhibitions including Agri Malaysia, MBAM OneBuild and the Malaysian International Food and Beverage Trade Fair..
Nexible Solutions Sdn Bhd, a subsidiary under the IT solution sector, provides business-to-business software products to its customers. Its flagship product, OutPerform, is an artificial intelligence-powered sales automation software that enables clients to manage new leads and customer relationships.
Website: www.catchadigital.com
LinkedIn: www.linkedin.com/company/catcha-digital-berhad/